The claim is the product. Everything else is administration around it.
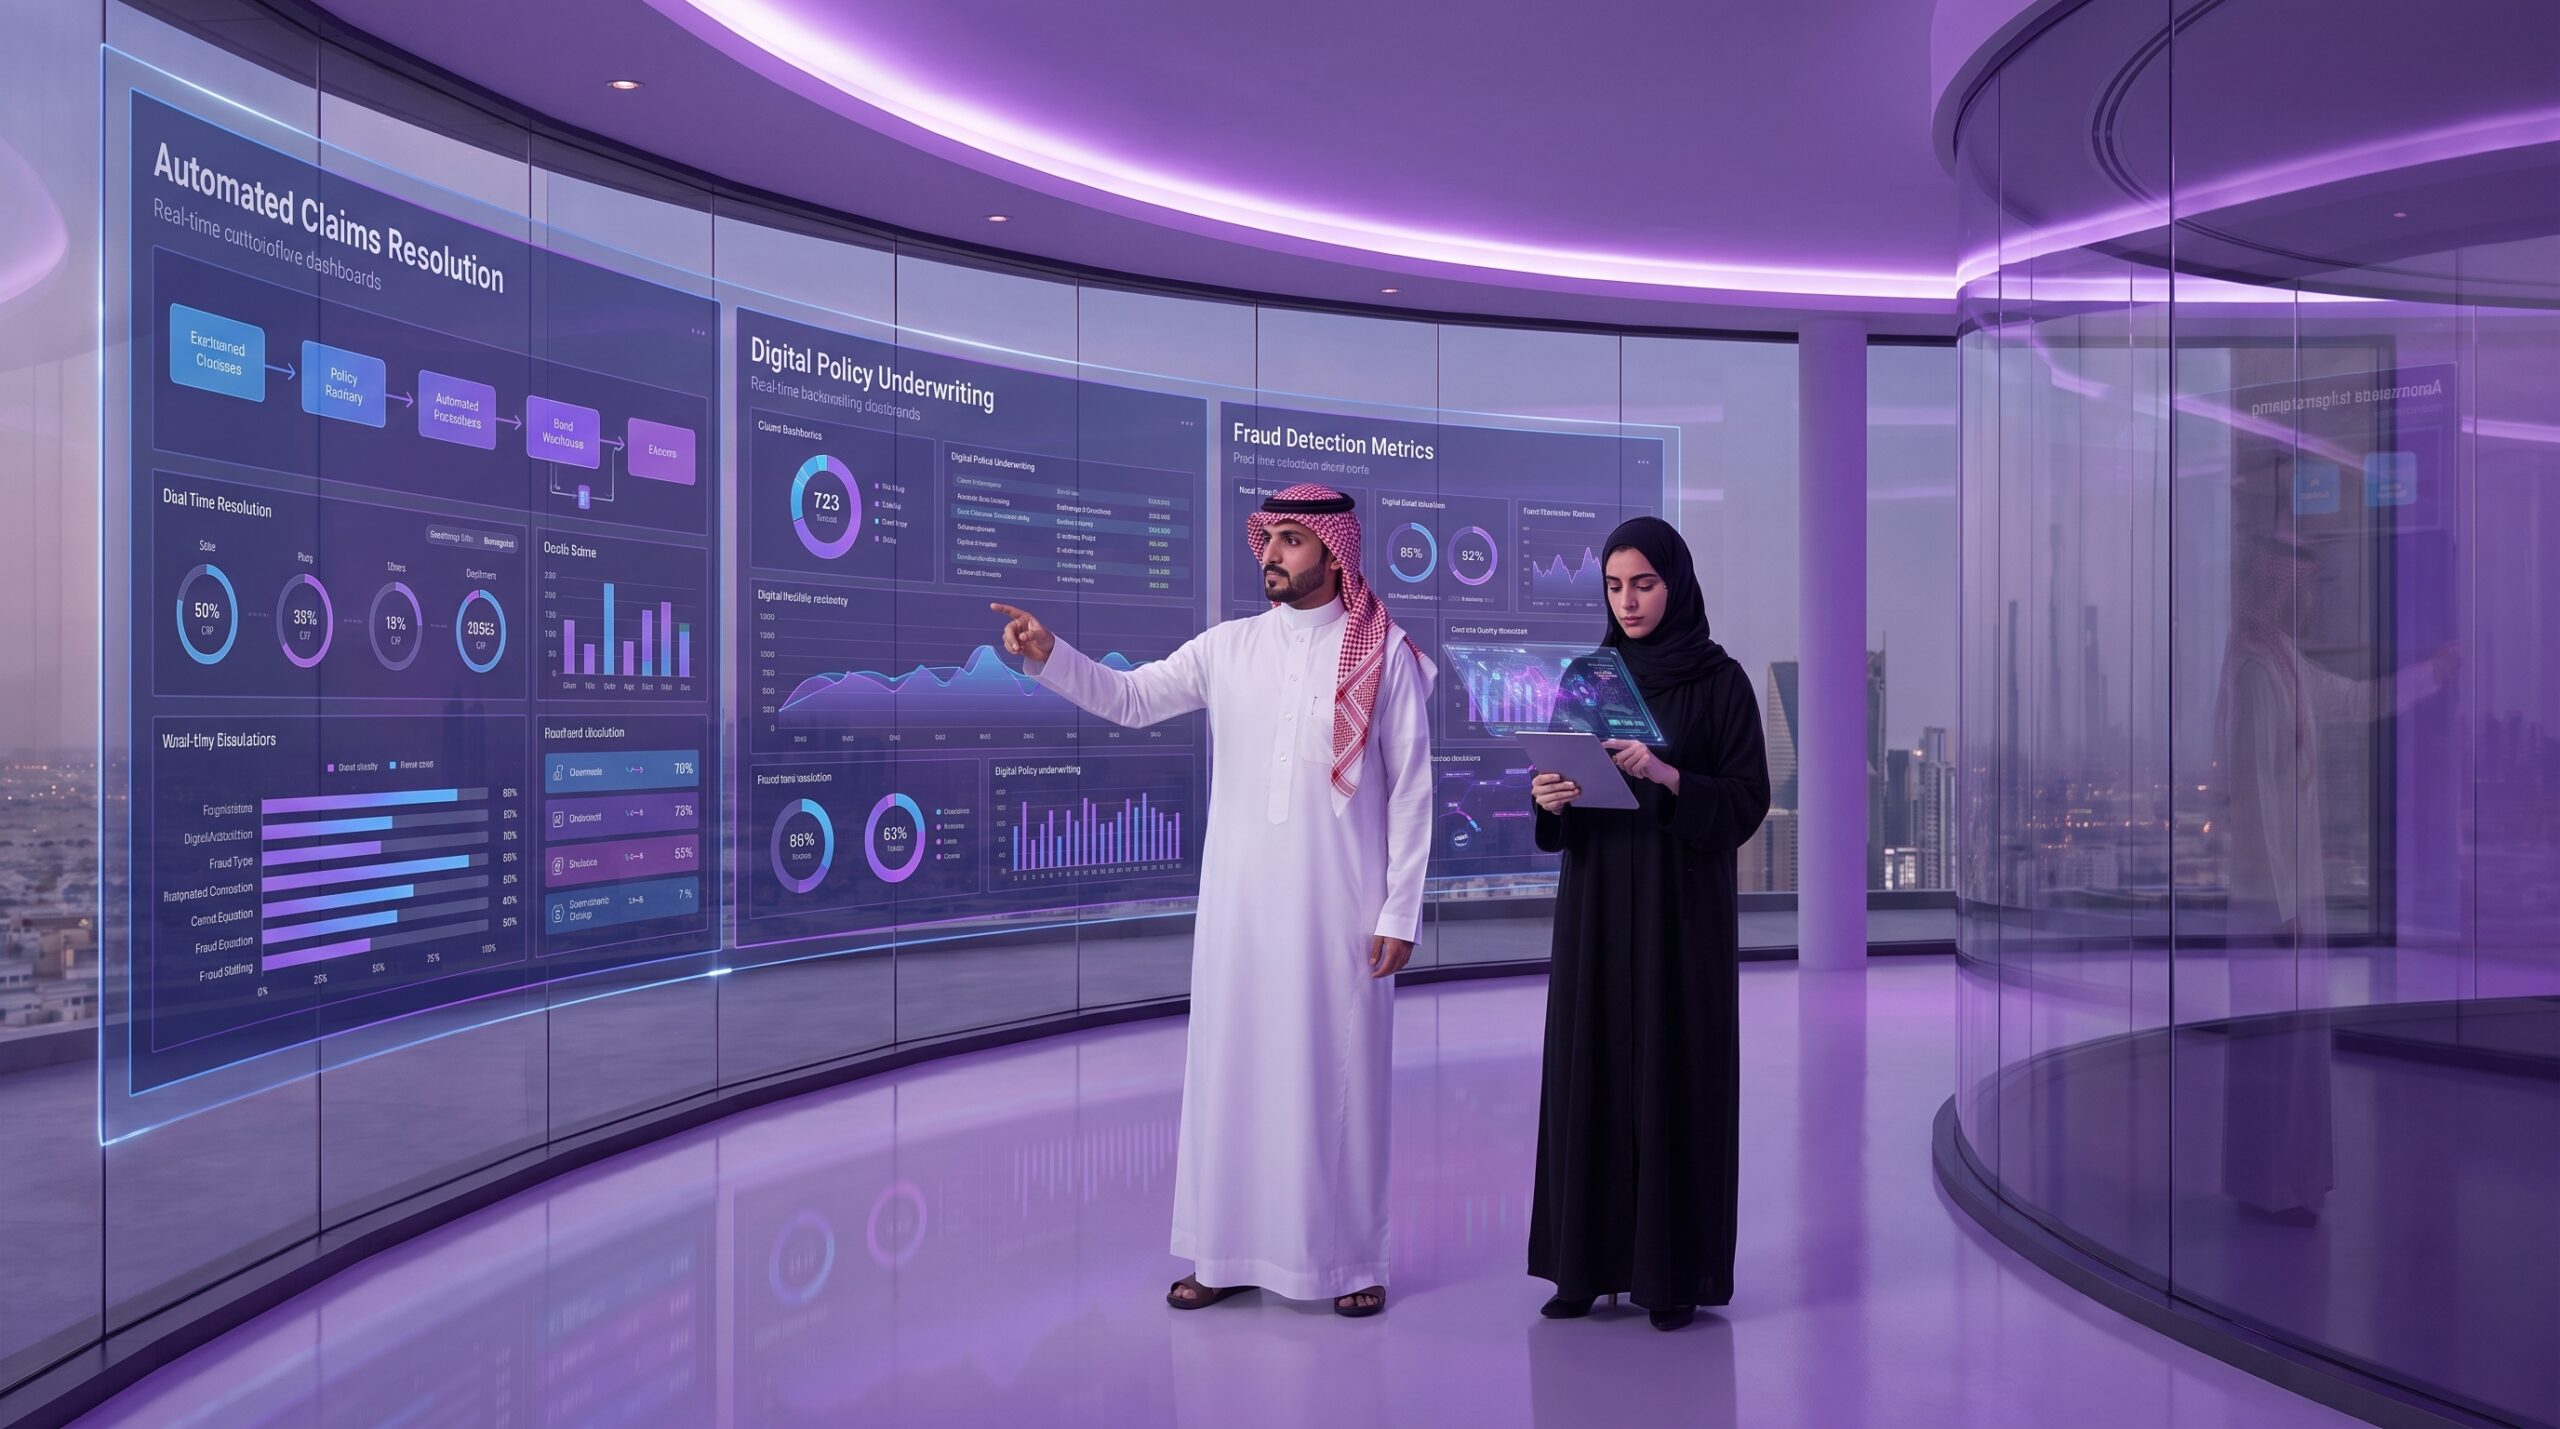
A policyholder forms a view of an insurer during a single event, typically an adverse one, and almost entirely on the basis of how long it took and how often an explanation was required. X-Shift addresses the two factors that determine that view: the service layer that manages the enquiry and the case, and the assessment step that historically required an individual to travel before any progress could be made.
Engagements with insurers and brokers concentrate on the claim lifecycle and on the servicing around it. The claim is where the relationship is determined; policy servicing is where it is eroded.
The work is positioned above the core policy and claims systems that the insurer already operates. X-Shift does not underwrite, price risk or adjudicate claims. X-Shift is accountable for the service layer, the evidence trail and the integration with the insurer's systems of record.
01
A claims service assessment that establishes where elapsed time is spent between first notification and settlement.
02
A case and channel implementation that provides a single claim record behind the call, the app, the broker and the email.
03
A remote assessment capability for damage and condition, enabling evidence to be captured without a site visit where attendance is not required.
04
A managed arrangement in which X-Shift operates first-line claims and policy servicing against agreed measures.
Priority areas
Where X-Shift typically creates value in this sector
Elapsed time is the first priority, as it is what the policyholder experiences. Consistency of assessment is the second, as it is what the regulator and the loss ratio reflect.
Insurers measure handling time. Policyholders measure the wait.
Most claims teams are not slow at the work; they are slow between the work. The file waits for an assessor, then for an approval, then for a payment instruction, and each wait is invisible within a system that records only touchpoints. The policyholder experiences the gaps, calls to enquire about them, and thereby generates the contact volume that slows the next claim.
The second pressure is consistency. Two adjusters assessing similar damage should reach similar conclusions, and where they do not, the insurer bears both the leakage and the complaint. That is an evidence and criteria issue before it is a training issue.
What changes
What the operation can demonstrate afterwards
01
Where elapsed time is spent in a claim, by stage, rather than by team.
02
Which assessments were completed remotely and which required attendance.
03
Whether similar claims were assessed consistently, with the evidence behind each.
04
The reasons for which policyholders made contact, and which of those contacts were generated by the process itself.
05
Which brokers and channels generate rework, and why.
Portfolio
The full portfolio applied in insurance
Solutions, services and platforms that X-Shift applies with insurers, brokers and third-party administrators.
Working as oneInsurance connects Solutions, Services and Platforms.
No. It eliminates the journey where the journey does not add value. The adjuster continues to apply judgement, make decisions, and attend where the condition cannot be verified visually or where testing is required. What changes is that straightforward cases no longer wait behind complex ones in the same travel schedule.
Can this operate without replacing the existing policy and claims systems?
Yes, and that is the standard approach. The service and case layer operates above them through integration, so that the system of record remains unchanged. Where the core system cannot expose the required data, X-Shift will state this during design rather than discover it during build.
How is evidence from a remote assessment treated?
Captured against the specific criterion it answers, versioned, and retained with the case. The metadata recorded, and the additional verification controls applied, are defined per inspection type against the insurer's own requirements rather than assumed.
Where is the benefit limited?
Where the delay arises in underwriting authority, reinsurance referral or a payment process outside the service layer, an improved front end changes the experience but not the elapsed time. This should be established before scoping.
Next
Where to take this next
01
Commence with the claim clock
Establish where elapsed time is spent between first notification and settlement, stage by stage, before any change is made.
Applicable where handling time appears acceptable but policyholders continue to describe the claim as slow.
Select one claim type in which assessment is visual, conduct it remotely against defined criteria, and compare cycle time and consistency with the current process.
Applicable where assessor scheduling is the constraint on settlement speed.
Applicability is determined by the business requirement, not by the sector. Every platform listed is deployable in insurance; those marked are the most frequently requested.